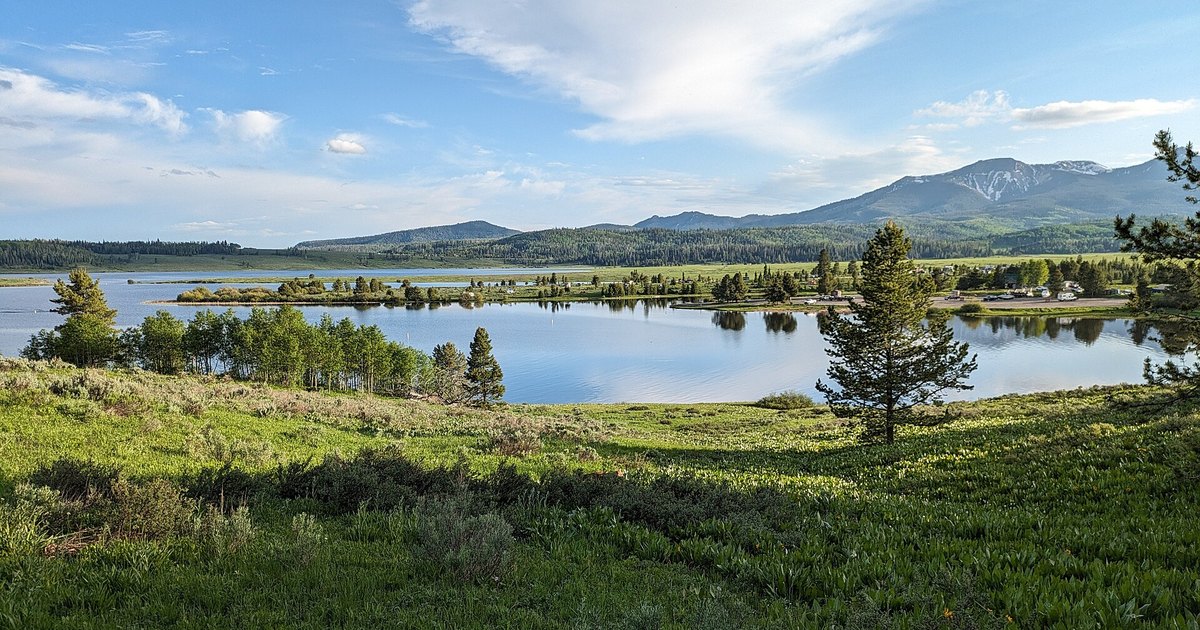
Forested mountain home country in Routt County, Colorado
Mountain-home insurance · Wildfire risk · The FAIR Plan · Your deal

Insuring a mountain home, honestly.

In the Colorado high country, insurance has quietly become one of the biggest questions in a transaction. Carriers have pulled back, premiums have climbed, and in wildfire country the ability to actually bind a policy can make or break a deal. I'm a broker, not an insurance agent — but I'll tell you how this really works, and make sure you get a real quote early, when it still protects you.

The real version

Colorado is a genuinely hard insurance market right now, and it's real, not marketing. Non-renewals have risen sharply over the last several years, and some large carriers stepped back from writing new wildfire-exposed policies (as of 2025–26 — carrier appetite shifts constantly, so any specific carrier is worth verifying). Premiums have climbed statewide. For a home in forested, wildland-urban-interface terrain, that pressure lands harder.

Here's the nuance most listings skip. Statewide, hail — not wildfire — is actually the single biggest driver of homeowners premiums, though wildfire's share runs toward the high end for mountain and WUI properties. Most mountain homes are still insurable, often at higher cost or through specialty carriers. And the outcome is deeply property-specific: it depends on the parcel's wildfire score, its fire protection district, the mitigation already done, and which carrier is looking at it. So I won't tell you a home is "fine" or "uninsurable." I'll tell you to get a real quote on the specific property, and help you do it in time to act on what it says.


What's actually going on

Four things worth understanding before you buy.

The market

A hard market, not a closed one

Non-renewals up, premiums up, some carriers writing less new business in wildfire zones (as of 2025–26). But "harder and pricier" is not the same as "impossible." Most homes still get covered — the question is at what cost, and through whom.

Last resort

The Colorado FAIR Plan exists

Colorado's insurer of last resort began taking applications in April 2025. It's fire-only, pays actual cash value (not full replacement), excludes liability and loss-of-use, and is capped (reported around $750K for residential). Most owners pair it with a wrap-around policy. Confirm current terms at coloradofairplan.com.

Mitigation

Mitigation now has to count

A Colorado law (HB25-1182, effective July 1, 2026) makes insurers using a wildfire score disclose it, credit property- and community-level mitigation, and offer an appeal. It doesn't promise a set discount, and it doesn't bind surplus-lines carriers — but documented mitigation is now leverage.

Your deal

Insurability can make or break it

Lenders require bound insurance before funding. If coverage can't be secured — or the premium blows past what a buyer qualifies for — the deal can die. This is why the quote belongs in due diligence, not at closing.

Figures and carrier specifics above are reported as of 2025–26 and are illustrative, not guarantees; wildfire scores, premiums, and insurability are property- and carrier-specific. I'm a licensed real estate broker, not an insurance agent — always get a quote from a licensed insurance professional for the actual property.

What you can do about it

Mitigation, and the help that's already here.

Wildfire risk on a given home isn't fixed — a lot of it is the first few feet around the structure. The recognized benchmark is the IBHS Wildfire Prepared Home standard, which starts with a strict noncombustible zone in the first five feet around the house and deck (no vegetation, wood mulch, wood fencing, or stored combustibles), plus ember-resistant vents, a clean fire-rated roof, and defensible space worked outward in zones. Keep receipts and photos of everything — documentation is what lets you claim a mitigation credit or appeal a wildfire score.

Routt County backs this up with real, homeowner-facing resources. The Routt County Wildfire Mitigation Council (routtwildfire.org) offers free Home Ignition Zone evaluations, free chipping, and resident rebates for eligible work. CSU Extension – Routt County publishes defensible-space and rural-living guidance, and the local fire protection districts and the Colorado State Forest Service run mitigation grant programs. One more local note: Steamboat Springs adopted a Colorado Wildfire Resiliency Code effective July 1, 2026, which affects materials and defensible space for new construction and many remodels in WUI areas — worth knowing if you're buying to build or renovate.

Timing is everything

Buying or selling — do this early.

If you're buying

Quote it during due diligence

Get a real, bindable insurance quote on the specific property inside your inspection window, before you remove contingencies. Knowing the premium — and whether a carrier will even write it — in time to renegotiate, walk, or plan mitigation is the single most important step. Not a surprise at the closing table.

If you're selling

Know your home's picture first

Insurability now affects saleability and price. A home that's hard or expensive to insure draws a narrower buyer pool and risks fall-through. Knowing your property's wildfire score, documenting mitigation, and understanding the insurance picture before you list lets us get ahead of it. Thinking of selling? Start here.

Common questions

Mountain-home insurance, straight answers

Is it hard to insure a mountain home in Colorado?

Harder than it used to be, yes — non-renewals are up, premiums are up, and some carriers have pulled back from new wildfire-zone policies (as of 2025–26). But most mountain homes are still insurable, often at higher cost or through specialty carriers. The key is to get a real quote on the specific property rather than assume either extreme.

What's the Colorado FAIR Plan, and is it "insurance"?

It's the state's insurer of last resort, open for applications since April 2025. Think of it as a fire-only backstop you build around: it covers fire and lightning on the dwelling and contents (wind/hail/vandalism optional), pays actual cash value not full replacement, excludes liability and loss-of-use, and is capped (reported around $750K residential — below the rebuild cost of many mountain homes). You reach it only through a licensed agent after being declined by admitted carriers, and most owners add a wrap-around policy. Confirm current caps and terms at coloradofairplan.com.

Will wildfire mitigation actually lower my premium?

It now has to be credited. HB25-1182 (effective July 1, 2026) makes insurers that use a wildfire score disclose it, credit property- and community-level mitigation, and offer an appeal. It doesn't guarantee a set dollar discount, and it doesn't apply to surplus-lines carriers. Documented mitigation to the IBHS Wildfire Prepared Home standard is your strongest lever — keep the receipts and photos.

Can an insurance problem actually kill my purchase?

Yes. Lenders require bound hazard insurance before they'll fund, so if coverage can't be secured or the premium pushes the payment past what you qualify for, the deal can collapse — one of the more common fall-through causes in wildfire country. That's why the quote belongs in your due-diligence window, not at closing. Cash buyers aren't bound by lender rules but still carry the uninsured-loss risk.

Where do I get mitigation help in Routt County?

The Routt County Wildfire Mitigation Council (routtwildfire.org) offers free Home Ignition Zone evaluations, free chipping, and resident rebates. CSU Extension – Routt County has defensible-space guidance, and the fire protection districts plus the Colorado State Forest Service run grant programs. I can point you to the right one for a specific property, and I'll help you factor all of it into the deal.

Free guide

Get the Routt County Buyer's Guide

An area-by-area read on Steamboat, Hayden, Oak Creek, Stagecoach and North Routt: what each place is really like, and what to weigh — including diligence items like wildfire and insurance — before you buy. Just your email; I'll send it right over.

One email, no spam. Unsubscribe anytime. Prefer to talk? Call or text.

Got a specific mountain home in mind?

Send me the property. I'll help you read the wildfire and insurance picture alongside the water, access, and the rest — and get a real quote in front of you early, while it still protects the deal.

Last updated: October 28, 2026
Insurance details reported as of 2025–26 and subject to change; this page is general information from a real estate broker, not insurance advice — confirm specifics with a licensed insurance professional and the Colorado Division of Insurance (doi.colorado.gov).